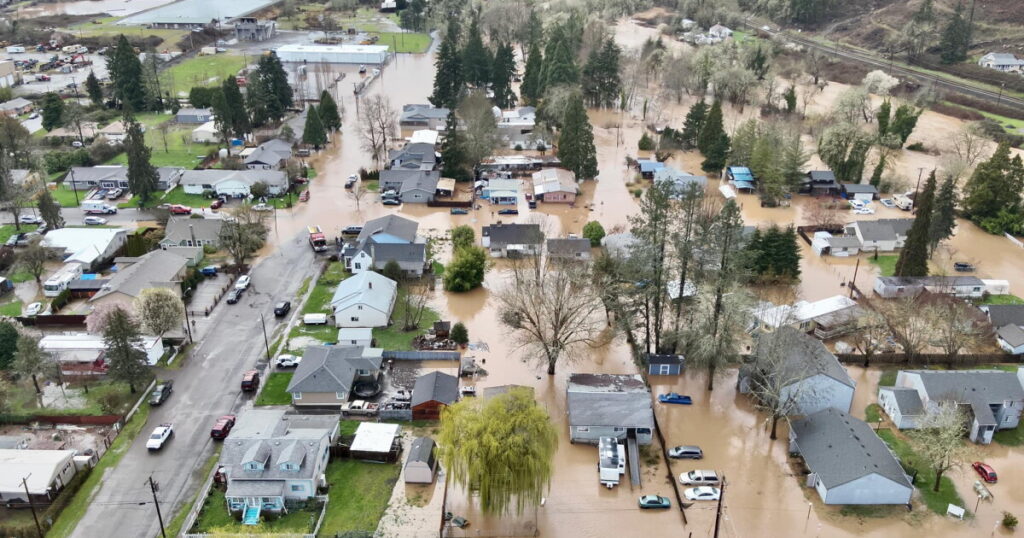
A growing number of homeowners are getting dropped by their insurance company after filing a single, often minor claim, sometimes one they weren’t even at fault for, as insurers lean more heavily on updated climate-risk modeling to decide who to keep covering.
How This Actually Plays Out
The pattern is consistent: a homeowner files a routine claim, storm damage, a break-in, a car hitting a fence, and rather than just processing it, the insurer’s underwriting model flags the property’s zip code as newly higher-risk and declines to renew the policy at all. Once dropped with an active claim on record, finding a new standard policy on that same home becomes difficult, sometimes pushing homeowners onto “force-placed” insurance arranged by their mortgage lender, which typically costs significantly more than a standard policy for less coverage.
Why It’s Happening More Now
Insurers have been updating their underwriting models more aggressively as climate-related claims, wildfire, flood, severe storm damage, have grown more frequent and expensive nationally. That’s pushed some companies to reduce their exposure in specific zip codes altogether rather than adjust individual premiums, which is why homeowners with clean claims histories can still get non-renewed if their location alone gets reclassified.
What Homeowners Can Actually Do
Before filing a claim under a certain dollar threshold, get a repair quote first: many homeowners are better off paying for a small repair out of pocket than filing a claim that could trigger a non-renewal review, since claims history follows the property, not just the policyholder. If you’re already facing a non-renewal notice, an independent insurance broker who works with multiple carriers, rather than a single-company agent, can often find surplus-lines coverage that’s still meaningfully cheaper than force-placed insurance. Some states also run FAIR Plans, state-backstopped insurance pools for homeowners who can’t get standard coverage, which are worth checking before accepting a force-placed policy by default.
The Longer-Term Fix Isn’t in Homeowners’ Hands
State insurance regulators in several high-risk states have started requiring insurers to justify non-renewal decisions tied to climate modeling rather than actual claims history, but that regulatory shift is uneven across states and still developing, meaning homeowners in the meantime are largely on their own to shop aggressively and document their property’s actual risk profile if they want to contest a bad decision.
Related from BeezLoop: Surveys Say Between 48% and 63% of Americans Live Paycheck to Paycheck, The 10-Year Treasury Hit 5.12%. Here's What That Does to Your Mortgage, Your Car Note and… and The Fed Raised Rates.