
AI is no longer only a technology story. It’s an economic story, a trade story and an infrastructure story. The risk isn’t that the boom is fake. It’s that a genuine boom can still conceal an uneven economy underneath it.
The short answer: then we would be measuring investment and calling it health. We can’t yet tell the two apart, and anyone claiming certainty is guessing. What separates them is whether the money moving into AI eventually shows up in productivity, wages, prices and services, or only in spending on servers and chips. Below is what that evidence would look like, and why it isn’t in yet.
The receipts
The World Trade Organization’s World Trade Report modelled AI’s effect on global commerce and found it could lift global trade by roughly 34% to 37% by 2040 and global GDP by around 12% to 13%, but only if gaps in adoption and capacity are bridged. WTO Director-General Ngozi Okonjo-Iweala noted that access to AI and the ability to participate in digital trade remain highly uneven.
The investment is real too. Stanford’s 2026 AI Index puts U.S. private AI investment at $285.9 billion in 2025.
Those are enormous numbers. They also invite a question that’s easy to skip: what if a booming AI economy isn’t the same thing as a broadly healthy one?
The gap between averages and experience
This isn’t an argument that the growth is illusory. It plainly isn’t. The problem is distribution. An economy can have one sector growing extremely fast while most households face high costs, weak demand or financial strain. The average looks fine. The lived experience varies enormously.
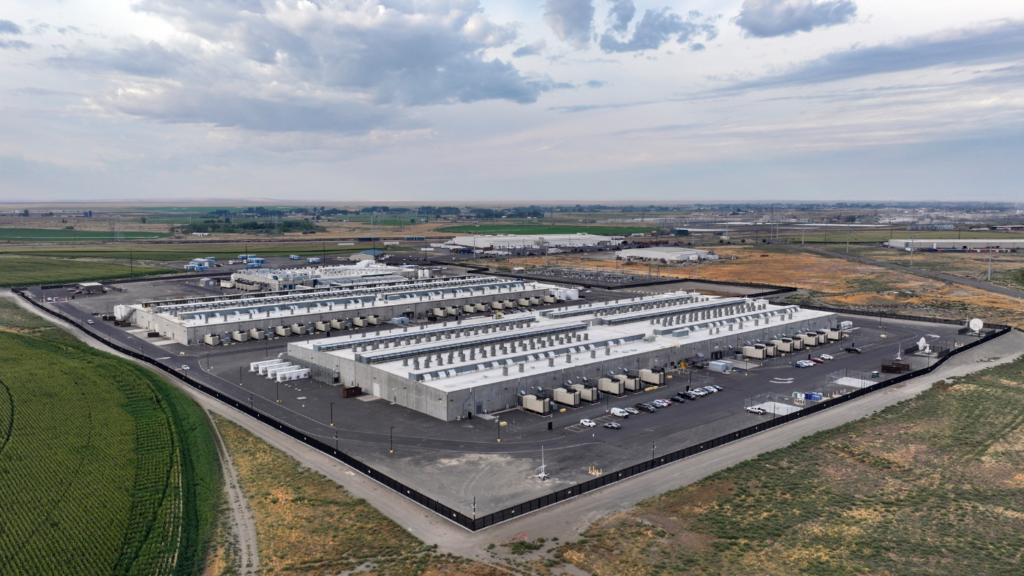
AI makes that tension unusually visible because its infrastructure is so physical. Data centers need electricity, land, networking hardware and capital. Chips need specialized supply chains. Someone has to be willing to spend heavily on compute. And the companies deploying it need productivity gains large enough to justify what they spent.
That last condition is doing a lot of quiet work. A forecast of what AI could add to global GDP isn’t a promise that workers, cities or households share it. Strong AI-related trade doesn’t tell us whether productivity gains became higher wages, lower prices, better services or steadier employment.
The human cost
Some of it’s already arriving as a utility bill. The electricity for this buildout gets socialized through rates unless somebody intervenes, which is why the House passed a bill 417-3 aimed at making data centers pay their own grid costs. It’s a bill that, read closely, only asks states to consider doing it.
The better questions are concrete. If companies spend billions on AI infrastructure, what return do they need? If the productivity gains fall short, who absorbs the loss? If they arrive, where does the benefit land? And if AI makes some work dramatically cheaper, does that show up as improved living standards or as margin?
The AI boom is real. Our concern is that we’re measuring the wrong thing. Investment and trade figures tell us enormous sums are moving. They don’t tell us whether the gains will be broadly shared, whether the spending earns its expected return, or whether the resulting economy is more resilient or less.
We think a genuine economic transformation should eventually appear in productivity, wages, business formation, consumer prices and services, not only in spending on servers and chips.
The open question
If AI becomes one of the largest sources of investment in the world, what happens if the gains concentrate among the companies and owners of the infrastructure while the costs of the transition are spread much more broadly?
What happens next
Watch productivity data, corporate AI spending, data-center construction, electricity demand, semiconductor investment, labor-market shifts, and any sign that consumers are receiving lower prices or better services. Those will tell you more than another headline announcing that AI is changing everything. The same distribution question runs through who actually absorbs the cost of higher interest rates.
WTO Director-General Ngozi Okonjo-Iweala has been careful to pair the projections with a caveat, noting that “access to AI technologies and the capacity to participate in digital trade remains highly uneven.” That unevenness is the whole question.

[…] headcount and spending, and it lines up with what the rest of the industry is doing. We wrote about how much of the current economy is riding on that bet, and this is what the inside of the bet looks […]
[…] Watch for incident-reporting requirements, independent testing regimes, rules governing high-risk uses, and whether companies publish enough for outsiders to evaluate their safety claims. Watch the money too. The same boom driving these deployments is reshaping trade and investment in ways that may not be as broadly healthy as the headline numbers su…. […]
[…] Watch inflation readings, employment data, consumer spending, and auto-loan costs. The next real story is not the rate number. It is whether the economy responds to it. The same distribution question sits underneath whether the AI boom is a broadly healthy economy or one very fast sector carrying an uneven one. […]
[…] of this happens in a vacuum. We wrote about how much of the current economy is riding on the AI bet and about consumer sentiment sitting near a record low. A generation entering the workforce is […]
[…] from BeezLoop: 7 in 10 Americans Don't Want a Data Center Near Them, AI Is Booming and Who Actually Pays More Now That ACA Subsidies Expired: A Breakdown by Age, Income, and Job […]